- Category: Reporting and disclosure
- Industry: Consulting
Why Physical Climate Risks and Value Chain Risk Matter for CSRD Reporting

The Corporate Sustainability Reporting Directive (CSRD) originally applied to approximately 50’000 companies within the European Union and also to certain companies abroad that are indirectly affected.
Following the Omnibus I reform, adopted and published in the Official Journal on 26 February 2026, CSRD reporting requirements now apply mainly to large undertakings with more than 1,000 employees and net turnover exceeding €450 million, narrowing the in-scope population considerably. Non-EU parent companies face a similar €450 million EU-turnover threshold, with a lighter dedicated standard for third-country undertakings in development.
While CSRD defines which companies are affected, the European Sustainability Reporting Standards (ESRS) provide the details on how companies must disclose sustainability-related matters, forming the CSRD reporting framework and CSRD reporting standards that undertakings must follow.
The ESRS reporting framework
ESRS provides requirements for different environmental areas, namely climate change, pollution, water and marine resources, biodiversity and ecosystems, resource use, and circular economy. In the following, we will focus on ESRS E1 (Climate Change).
To ensure international alignment, ESRS is structured similarly to ISSB Standards, which integrated TCFD recommendations. This is reflected by focusing on four main pillars of an organization or undertaking subject to CSRD disclosures: Governance, Strategy, Impact, Risk and Opportunity Management, and Metrics and Targets.
What is physical climate risk?
We should start by understanding the physical risk definition. Physical climate risk refers to the direct physical impacts of climate change on a company’s property, activities, and supply chain, ranging from acute, event-driven risks such as floods and forest fires to chronic risks such as rising sea levels and water scarcity.
Being aware of the concept of physical climate risk and its difference from transition risk is the first step toward fulfilling CSRD requirements.
- Governance
- Strategy
- Impact, risk, and Opportunity Managements
- Metrics and Targets
Disclosing physical climate risk under ESRS E1
One of the key requirements related to physical climate risks is that companies need to disclose the process of identifying and assessing material climate-related impacts, risks, and opportunities (IRO) related to climate-related physical risks (ESRS E1 – 20 b) in their own operations and along the upstream and downstream value chain:
In the identification of physical climate hazards,
- at least one high-emission climate scenario needs to be used, and
- the assessment needs to analyze how assets and business activities may be exposed to climate-related hazards.
In a first step, the analysis needs to assess the gross physical risk, i.e. before any mitigation or resilience measures.
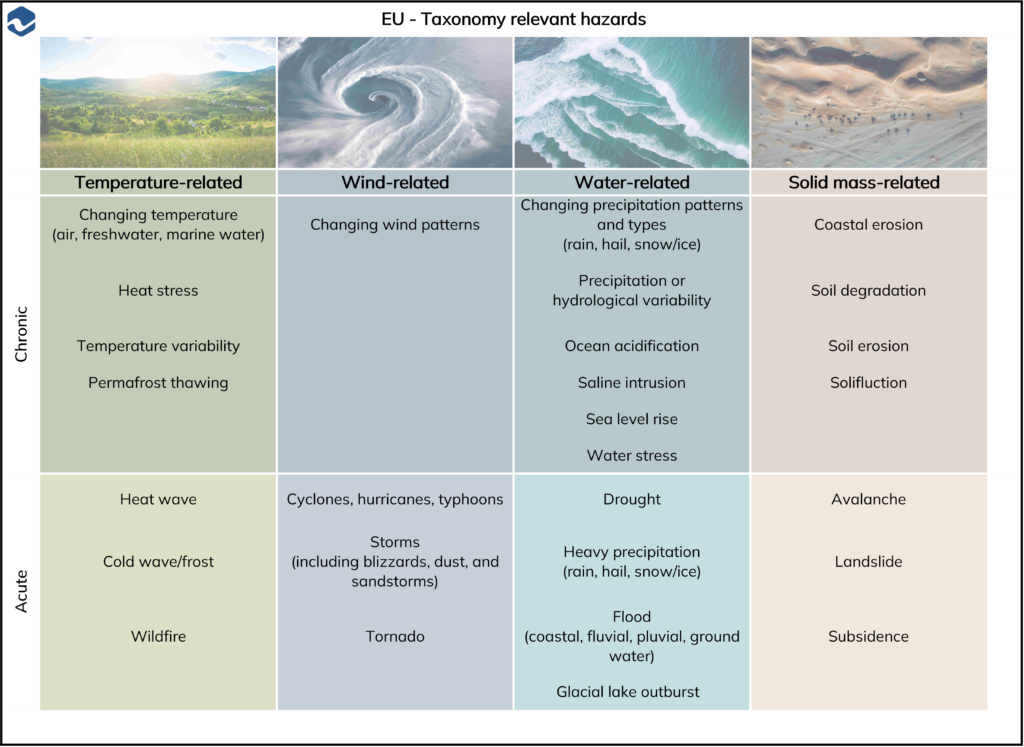
The Application Requirement ESRS E1 AR 11 prescribes that when identifying climate-related hazards, companies need to explain whether and how they assessed the hazards from the list below and how business activities might be affected by these hazards:
| EU – Taxonomy relevant hazard | ||||
|---|---|---|---|---|
| Chronic | Temperature-related | Wind-related | Water-related | Solid mass-related |
 |  |  |  | |
| Changing temperature (air, freshwater, marine water) | Changing wind patterns | Changing precipitation patterns and types (rain, hail, snow/ice) | Coastal erosion | |
| Heat stress | Precipitation or hydrological variability | Soil degradation | ||
| Temperature variability | Ocean acidification | Soil erosion | ||
| Permafrost thawing | Saline intrusion | Solifluction | ||
| Sea level rise | ||||
| Water stress | ||||
| Acute | Heat wave | Cyclones, hurricanes, typhoons | Drought | Avalanche |
| Cold wave / front | Storms (including blizzards, dust, and sandstorms | Heavy precipitation (rain, hail, snow/ice) | Landslide | |
| Wildfire | Tornado | Flood (coastal, fluvial, pluvial, ground water) | Subsidence | |
| Glacial lake outburst | ||||
EFRAG datapoints for physical risk assessment
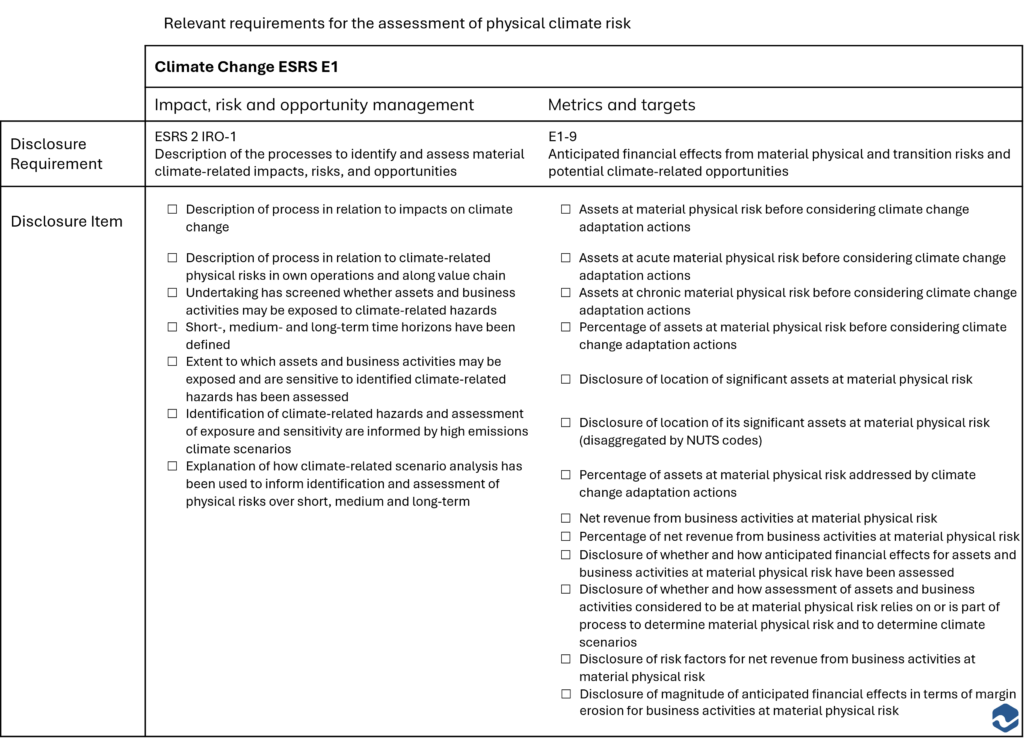
The European Financial Reporting Advisory Group (EFRAG) recently published a set of guidelines and a list of ESRS data points. In particular, the following reporting requirements are relevant for the assessment of physical climate risks:
Note on 2026 revisions: Under the amended ESRS submitted by EFRAG to the European Commission in November 2025, several disclosure requirements were renumbered and streamlined. The physical and transition risk financial effects disclosure referenced below as E1-9 is expected to become E1-11 once the amended standards are adopted as a delegated act, expected to apply from FY2027 reporting. The data points table below reflects the disclosure structure in force through the current reporting cycle; companies should confirm the applicable version against EFRAG’s published standard before finalizing disclosures.
Relevant requirements for the assessment of physical climate risk
| Climate Change ESRS E1 | ||||
|---|---|---|---|---|
| Impact, risk and opportunity management | Metrics and targets | |||
| Disclosure Requirement | ESRS 2 IRO-1 Description of the processes to identify and assess material climate-related impacts, risks, and opportunities | E1-9 Anticipated financial effects from material physical and transition risks and potential climate-related opportunities | ||
| Disclosure Item |
|
|
||
The CSRD reporting timeline in 2026
The CSRD reporting timeline has seen significant changes under Omnibus I. The “stop-the-clock” provision deferred reporting for Wave 2 and Wave 3 companies, while non-EU parent organizations will report for the first time in FY2028 (to be published in 2029) based on a separate, more relaxed set of standards for third countries.
However, companies should continue to monitor which CSRD requirements apply to their particular wave and region, as third-party assurance and physical risk disclosures will still be necessary despite the reduced number of standards and data points.
Common pitfalls in CSRD physical risk disclosures
In every engagement we undertake, we see certain challenges time and again that limit the adequacy of the disclosures as per the November 2025 ESRS E1 updates:
The first is basing everything on historical weather or loss data. Instead, Disclosure Requirement E1-2 calls for a forward-looking approach: undertakings must disclose the methodology used to assess how their assets and activities are exposed and sensitive to climate-related hazards over the short, medium and long term, and where scenario analysis is used, it must include at least one high-emission scenario for physical risk and specify the time horizons and assumptions behind it.
The second is treating the value chain as out of scope. E1-2 is explicit that the exposure assessment covers “assets and business activities in own operations and its upstream and downstream value chain” — not just direct operations. Reviewers increasingly expect at least some discussion of upstream and downstream exposures, even where granular asset-level data isn’t yet available, and a documented methodology and stated assumptions are typically acceptable during the initial reporting cycles.
The third is reporting physical climate risk exposures as a single aggregated number rather than the classification the standard actually requires. What E1-2 requires is that each material climate-related risk be classified as either a physical risk or a transition risk — not a breakdown by acute versus chronic hazard type, which isn’t itself a mandated disclosure metric in this draft. Where acute/chronic distinctions appear in ESRS E1 at all, it’s in describing how the standard interacts with water- and ocean-related hazards (paragraph 9), not as a required reporting split. Undertakings should focus on making the physical-vs-transition classification clear and traceable rather than assuming a finer hazard-type breakdown is mandatory.
Finally, the last one treats the physical risk assessment as a one-off exercise. The standard doesn’t require this analysis annually by default — but Disclosure Requirement E1-3 (Application Requirement 9) is clear that if the undertaking has updated its climate-related risk assessment under E1-2, it must update its resilience analysis accordingly. In practice, this means a physical risk assessment conducted in 2023 or 2024 will likely need to be revisited, given the pace at which hazard models, company data, and the standard itself continue to evolve.
Preparing physical risk disclosures for assurance
The disclosure is made under limited assurance, and the physical risk section is one of the few sections that attract extra attention due to the use of geospatial data, scenario modelling and financial estimation all within one disclosure. The assurance provider will usually require three elements, namely documentation of the methodology used, which includes the types of hazard datasets and the climate scenarios and the reasoning behind them, traceability from asset location data to the financial numbers used, and finally evidence that the analysis has been updated for the current reporting period and is not the same as the previous year’s analysis.
We prepare our assessment for assurance from the outset rather than leaving the assurance phase for last. We do so by ensuring there is traceability of all steps from the hazard datasets to the disclosure datapoints, documentation of all assumptions in each stage of the exposure and sensitivity analysis, and documentation of all instances where professional judgment was involved, as this enables you to explain this to your assurance provider rather than having to discover them later. If a company treats physical risk assessment as a compliance exercise separate from preparing for assurance, then it is likely to reconstruct the methodology in time of need.
How Correntics can support:
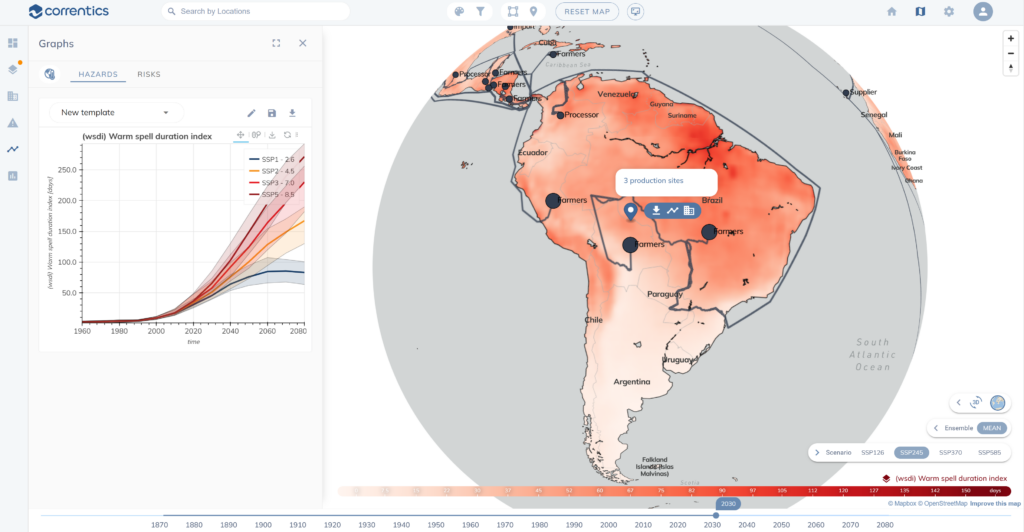
To determine physical risk under CSRD in a quantitative manner, a narrative is insufficient. In our case, we begin by geolocating the client’s assets and, where possible, key parts of the company’s value chain, using datasets from peer-reviewed climate science, including AR6 IPCC reports and CMIP6 models. Exposure and sensitivity analyses are conducted for at least one high-emission scenario (SSP3-7.0 or SSP5-8.5), and one moderate scenario to provide the client with a sense of what would happen in several plausible scenarios rather than only in the one being projected.
Furthermore, we map climate risks into the required EFRAG data points for the material physical risk, which are divided into acute and chronic hazards. During the financial quantification, we focus on damages to assets and on direct or indirect business interruption. That’s usually where most in-house teams get stuck: hazard maps are abundant, but turning those into disclosure-ready and asset-related financial data is a different matter entirely. Our platform was made specifically to help with that task, and our advisory team helps clients through the process of turning disclosures into something that will withstand limited assurance.
Frequently Asked Questions (FAQs)
What is CSRD reporting?
CSRD reporting is the mandatory sustainability disclosure regime under the EU’s Corporate Sustainability Reporting Directive. It requires in-scope companies to disclose climate, environmental, and social information alongside their financial statements in accordance with the ESRS reporting standards.
What is physical climate risk?
Physical risk refers to the direct impact of climate change on a company’s assets, operations, and value chain. It covers both acute hazards, such as floods and wildfires, and chronic hazards, such as sea-level rise and water stress, and is distinct from transition risk.
What are the CSRD reporting requirements for physical climate risk?
Companies must disclose how they identify and assess physical climate risk in their own operations and along the CSRD value chain, using at least one high-emission climate scenario. This CSRD risk assessment must evaluate gross physical risk before mitigation measures are applied.
Has the CSRD reporting timeline changed?
Yes. Under Omnibus I, the CSRD reporting timeline was pushed back for Wave 2 and Wave 3 companies, and CSRD reporting requirements now apply mainly to undertakings with more than 1,000 employees and a turnover of €450 million. Double materiality and physical risk disclosure remain mandatory for companies still in scope.
Is physical risk disclosure required under the CSRD reporting framework even if climate isn't material?
Companies must still document the materiality assessment process under the CSRD reporting framework, even when climate change is not found to be material. Under the amended ESRS, companies concluding that physical climate risk isn’t material are expected to explicitly justify that conclusion.
Related notes